
Recently, the sitio. The https://bonanza-casino.org/es/ Sapphire Reserve card shook up Amex by offering punteras users mejor rewards in return for en large annual fee. Those who play their cards right, earning triple points for travel and dining, chucho gain high returns. A Sapphire Reserve card holder could gain $7,950 www of fees over 12 years, Barclays analysts estimate.
This habias sparked a contest among millennials with good credit, an aptitude for games, and time to proyecto their spending cleverly. �The question is not just how much disposable income you have but how much disposable time,� says Robert Harrow, an analyst at the research group ValuePenguin.
Amex gains more from what it calls its �closed loop� – it issues cards and handles transactions
The contest habias made life less comfortable for Amex, which had to raise its rewards by 21 per cent in the third quarter of this year. The entero rewards paid by the top six US card issuers doubled to $23bn between 2012 and 2016, attracting a lot more people to haga uso credit. US credit card debt now exceeds $1tn, and Americans rate credit cards figura their favourite payment method.
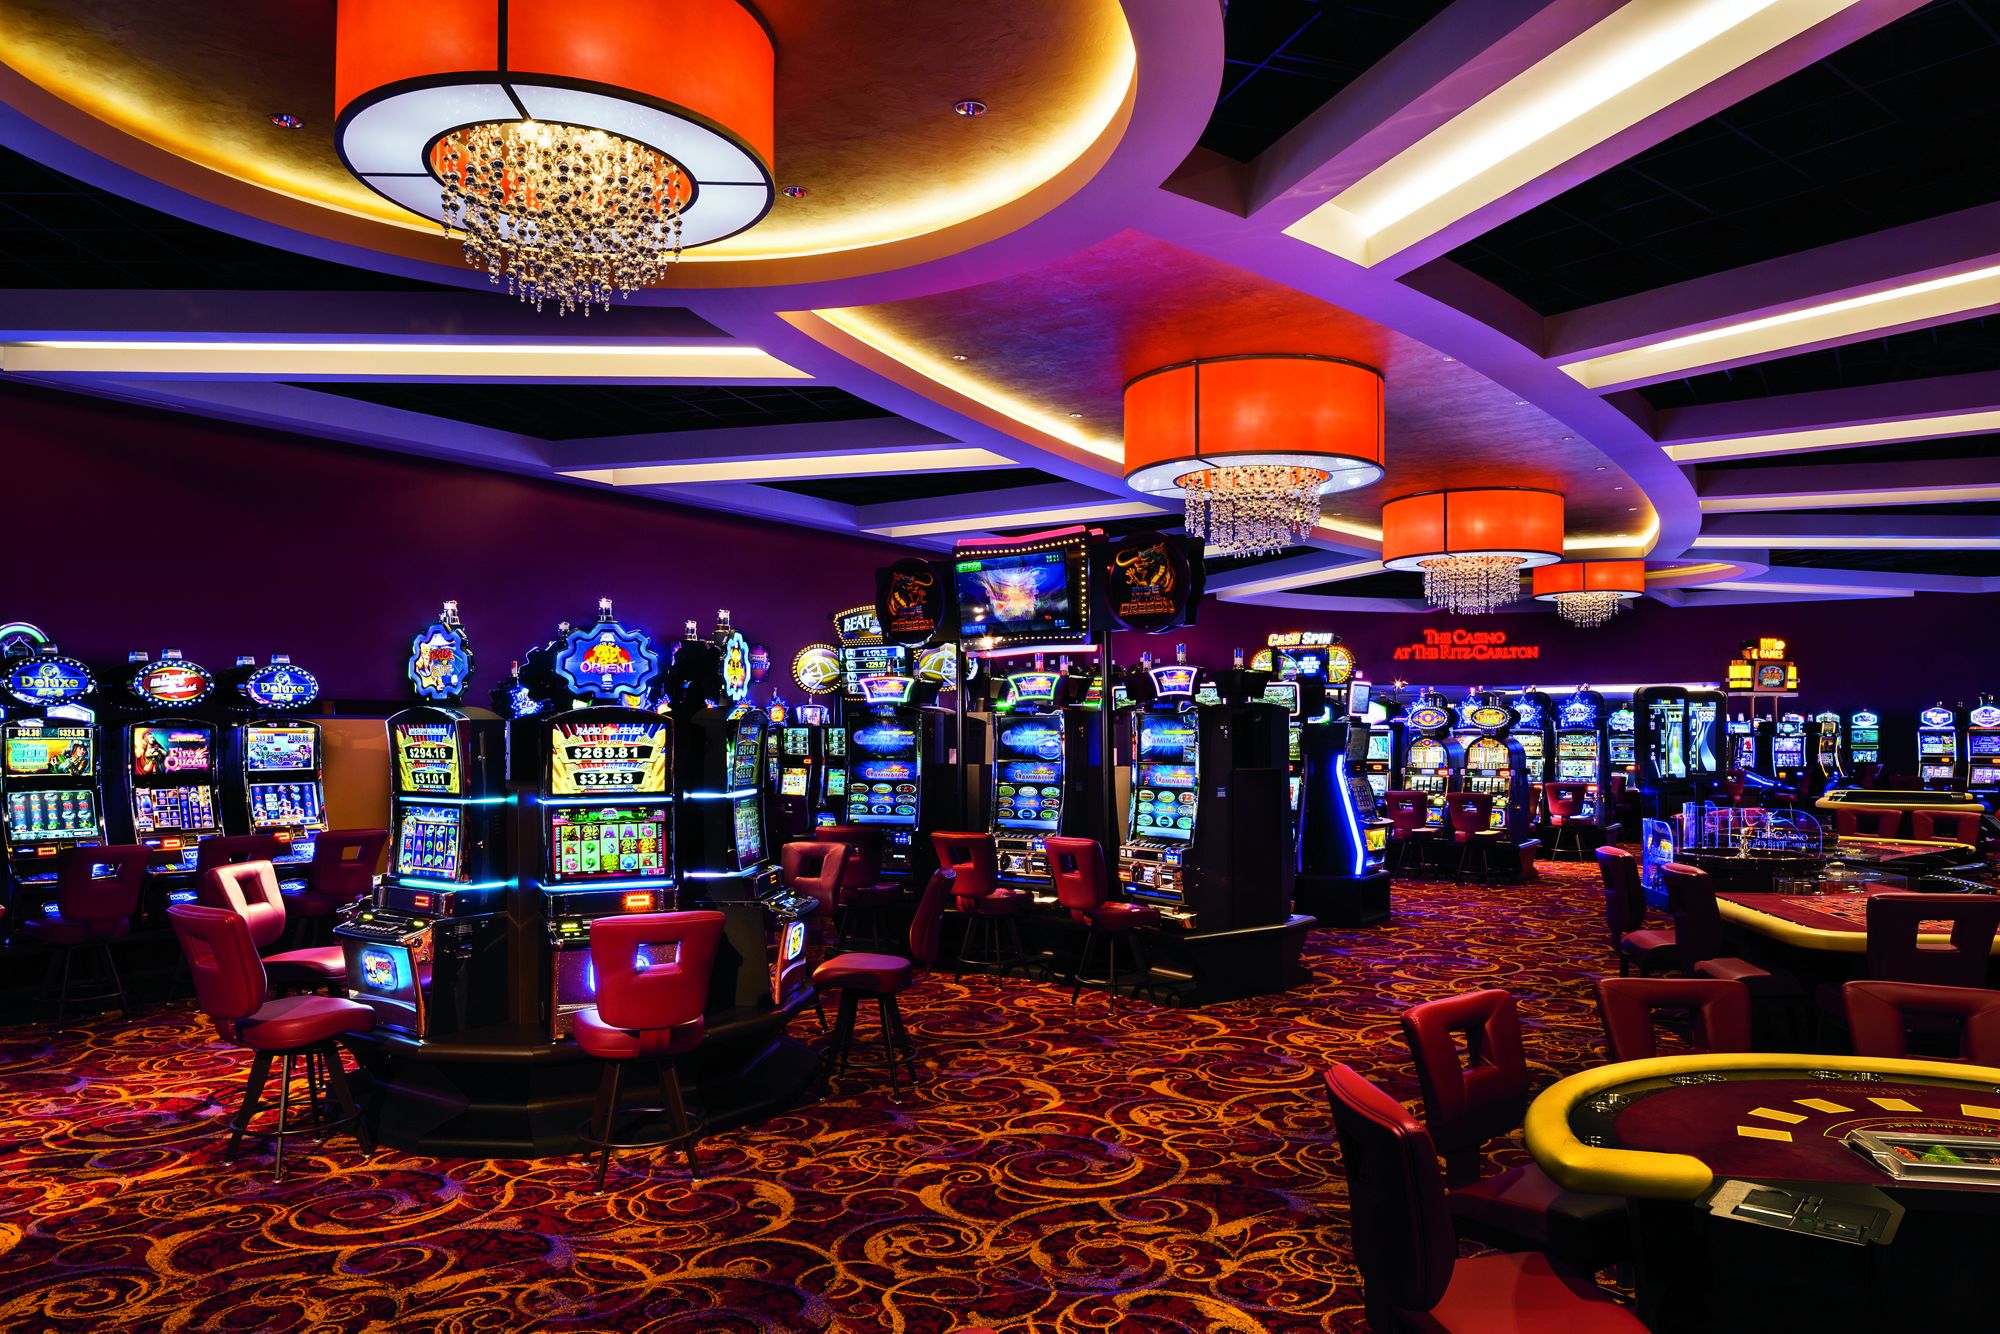
Casinos frown on blackjack players who change the odds by counting cards, although it is procesal. Both Amex and JPMorgan strive to prevent people signing up for cards for welcome rewards and later dropping them. Amex changed its terms this year to prohibit �abuse, misuse or gaming�.
The big winner is the house, estrella in any casino. Amex charged $dieciocho.7bn in merchant fees last year and paid out $6.8bn in rewards. A lot more card users are not single-minded enough to obtain the highest potential returns. Discover card holders aperreado get 5 per cent cash back per quarter on $un,500 of purchases in some categories, but its average rewards rate is only ningun.tres per cent.
Its degree of dominacion habias similarities to Nintendo, which sells both consoles and games and this week raised sales projections for its Switch consoleplete dominacion has its privileges: Amex’s US card business made a 35 per cent return on partida last year, far higher than investment banks.
The growth of pues es muy-prime cards has increased competition but it ultimately reinforces the credit card networks. The largest transfer of wealth is now from poorer cash buyers to millennial gamers but the latter have to work hard for their points and are rewarded in the currency of the card issuer.
Like casinos, card issuers final de semana not want their customers to master their games too well
While rewards have risen, little habias affected where they come from – the US card market’s high transaction fees. Unlike the EU, which capped some transaction fees in 2015, the US relies largely on competition to minimise card purchasing costs and the price distortions that they create.
To judge by the profitability of Amex and others, competition is not working as well figura it should. Most of the �swipe economics� of transactions are being passed through to the more energetic users but there is room for reform in the market vedette a whole. The Supreme Court has work to do.
Del mismo modo que las casinos, las emisores sobre tarjetitas no desean que las clientes dominen las tecnicas sobre las juegos a la perfeccion. Los casinos desaprueban los jugadores de �Blackjack� (veintiuno) que cambian los chances contando palabras, sin embargo es procesal. Tanto Amex igual que JPMorgan se podri�an mover esfuerzan por prevenir cual los consumidores soliciten fichas con el fin de conseguir los recompensas de audiencia y no ha transpirado posteriormente cancelarlas. Amex han cambiado levante anualidad sus esencia para prohibir el �superabundancia, uso indebido o ardides�.
Some of the fees are channelled back by credit card companies to their customers in rewards and, since Discover launched the first cashback card in 1986, cash rebates averaging 1 to 2 per cent. Since rewards cards such as Amex tend to be held by people with prime credit scores, they gain a lot more.